10 Best Comprehensive Car Insurance Plans in Hong Kong
Car insurance in Hong Kong is a legal necessity, but choosing the right plan in 2026 goes beyond the minimum third-party liability. With dense traffic, high repair costs, and frequent extreme weather, drivers need coverage that balances comprehensive protection with competitive premiums. Our evaluation criteria focus on annual premiums in HKD, claim settlement efficiency, customer service ratings, and unique value-added features like no-claims discount protection and courtesy car benefits. The best plans stand out by offering flexible deductibles, seamless digital claim filing, and coverage for windscreen and battery damage—common pain points for Hong Kong drivers. We also consider partnerships with local workshops for faster repairs. Whether you drive a luxury sedan, a compact city car, or an EV, the right policy should adapt to your usage and budget. This ranking highlights insurers that combine financial stability from major banks and global carriers with local market expertise. From HSBC’s bundled discounts to AXA’s 24/7 roadside assistance, each entry has been selected for its ability to deliver real peace of mind on Hong Kong’s demanding roads.
Top10Grid lets the community re-rank anything — this order is our editors' pick for now; use the buttons below to vote it up or down.

Current Rankings
- –#1
HSBC Car Insurance (Comprehensive)
It features a no-claims discount (NCD) protection that caps discount loss after an accident, a 60% NCD maximum, windscreen cover without NCD deduction, and rental car reimbursement while your car is under repair. Personal accident benefits of HKD 200,000 for the driver are included. Best for existing HSBC customers who can bundle for a multi-policy discount. A notable weakness: drivers under 25 face an additional young-driver excess on top of the standard policy excess.
Sourceshsbc.com.hk1 - –#2
AXA Hong Kong Comprehensive Car Insurance
Key features include a 24/7 roadside assistance hotline, a courtesy car after an accident, coverage for legal liability up to HKD 100 million, and new-for-old replacement for newer vehicles if written off. Windscreen and glass damage coverage is included. Best for drivers wanting maximum post-incident support. A weakness is an annual mileage limit; exceeding it can void certain benefits.
Sourcesaxa.com.hk1 - –#3
Hang Seng Bank Car Insurance (Comprehensive)
Its standout feature is a unique 'Reward No-Claims Discount' allowing policyholders to restore up to 3 years of NCD after a single at-fault claim. Other highlights include a personal accident benefit of HKD 300,000, a free replacement car for 14 days after a total loss, and coverage for personal belongings in the car up to HKD 5,000. A 10% discount applies for online applications. Best for drivers seeking bank integration with easy premium payment via Hang Seng accounts. A weakness: limited authorized repair workshops in the New Territories.
- –#4
DBS Hong Kong Car Insurance (Comprehensive)
Its standout is the 'Instant Claim' mobile app, enabling photo-based claim filing with a 48-hour turnaround for simple cases. Features include no-claims discount protection for up to 1 year, a courtesy car for 7 days, third-party property damage coverage up to HKD 10 million, and a free annual car inspection valued at HKD 800. Best for tech-savvy drivers preferring digital claims and banking integration. A notable weakness: high voluntary excess of HKD 6,000 for drivers aged 21-24.
- –#5
Standard Chartered Hong Kong Car Insurance (Comprehensive)
Standard Chartered’s comprehensive car insurance is tailored for high-net-worth clients, with premiums starting at HKD 6,200 for luxury vehicles. It offers a unique 'Premium Excess Waiver' that reduces the compulsory excess to zero for an additional premium of around HKD 800 per year. Other features include coverage for courtesy car for 30 days, personal accident benefits of HKD 500,000, and a 24/7 concierge service for emergency assistance. The policy also covers loss of use up to HKD 1,000 per day for 30 days. Best for owners of high-value cars (over HKD 500,000) who want minimal out-of-pocket costs. A weakness is the limited availability—only for Priority Banking customers.
- –#6
Zurich Insurance (Hong Kong) Comprehensive Car Insurance
Key features include a 'No Claims Discount Protector' that can help preserve NCD after a claim, a courtesy car benefit, and coverage for legal liability. Zurich also provides a 24/7 emergency hotline and a towing service for breakdowns. The policy includes a personal accident benefit for the driver. Best for drivers seeking a global insurer with strong local presence. A notable weakness is an early cancellation penalty on the policy term.
- –#7
China Taiping Insurance (HK) Comprehensive Car Insurance
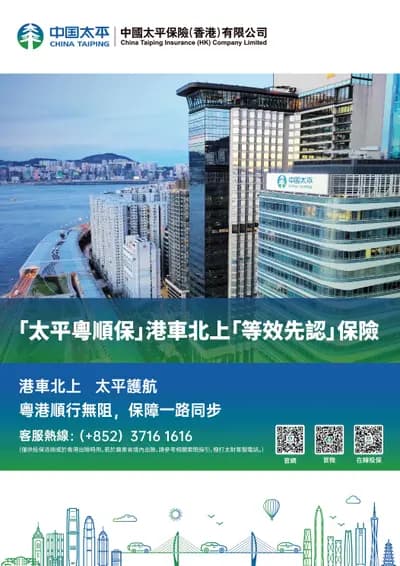
It features a generous NCD maximum of 60%, a courtesy car for 10 days, and coverage for third-party property damage up to HKD 20 million. The policy also includes a 'Battery and Windscreen Cover' with no excess for claims under HKD 3,000. A unique benefit is the 'Medical Expenses for Passengers' up to HKD 50,000 per person. Best for cost-conscious drivers who still want solid coverage. A weakness is the slower claim processing time—average 10 business days compared to the industry standard of 5.
- –#8
FWD Insurance Comprehensive Car Insurance
FWD’s comprehensive car insurance is designed for flexibility, with premiums starting at HKD 4,200 per year. Standout features include a 'Pay-As-You-Drive' option that calculates premiums based on actual mileage (starting at HKD 2,800 for low mileage), a courtesy car for 14 days, and coverage for legal liability up to HKD 30 million. The policy also offers a 'Claim-Free Bonus' of HKD 500 cashback after a year without claims. Best for drivers who drive less than 10,000 km annually. A notable weakness is the limited network of approved workshops—only 15 in Hong Kong, mostly on Hong Kong Island.
- –#9
BOC Group Life Assurance Comprehensive Car Insurance
This policy covers loss or damage to car accessories up to a set limit and offers car-wash perks at selected stations. Best for drivers who want a simple, no-frills policy from a trusted local bank. A weakness is the lack of 24/7 roadside assistance; help is only available during standard business hours.
- –#10
Liberty Insurance (Hong Kong) Comprehensive Car Insurance
This policy includes a 'Windscreen and Glass Cover' with a HKD 500 excess. Liberty offers a 5% discount for insuring two or more vehicles. Best for families with multiple cars. A notable weakness is the limited digital claim portal; most claims require a phone call, which can be inconvenient for tech-savvy users.
Frequently Asked Questions About Car Insurance in Hong Kong (2026)
## Is car insurance legally required in Hong Kong?
Yes. Every vehicle registered in Hong Kong must carry at minimum third-party liability insurance before it can be driven on public roads.
## What is a No-Claims Discount (NCD)?
An NCD is a premium reduction you earn for each year you do not make a claim. Several insurers on this list, including HSBC, Zurich, and China Taiping, offer NCD protection that prevents your discount from resetting after a single at-fault claim.
## What does 'comprehensive' cover that third-party does not?
Comprehensive plans typically add cover for damage to your own vehicle, windscreen and glass, fire, theft, and personal accident benefits for the driver — on top of the third-party liability that is legally required.
## How were these plans selected?
The plans on this list were compared on annual premiums in HKD, claim settlement efficiency, customer service ratings, and the breadth of add-on benefits such as roadside assistance and courtesy cars.
Car Insurance in Hong Kong: Common Questions
### Is car insurance mandatory in Hong Kong? Yes. Every motor vehicle used on a public road must carry at least third-party liability insurance under the Motor Vehicles Insurance (Third Party Risks) Ordinance.
### What is a No-Claims Discount (NCD)? An NCD is a premium discount that grows each year you do not make a claim. Many Hong Kong plans now offer an NCD Protector that prevents your discount from being reduced after a single at-fault claim.
### How much is the average annual premium in Hong Kong? Premiums vary widely by driver profile, vehicle make and model, and chosen add-ons. Comprehensive policies for private cars typically range from a few thousand HKD upward, and exact quotes must be obtained from the insurer.
### What is an 'excess'? The excess is the amount you pay out of pocket before the insurer covers the rest. For example, a HKD 500 windscreen excess means you pay the first HKD 500 of any windscreen claim.
How to compare no-claims discount protection across these plans
Nearly every plan on this list handles NCD protection differently, and the difference matters more than it looks at first glance. HSBC caps how much discount you lose after an accident rather than eliminating it. Hang Seng's 'Reward No-Claims Discount' can restore up to three years of discount after a single at-fault claim — one of the more generous terms here. Zurich's 'NCD Protector' prevents any loss after one claim per year, and China Taiping offers a flat 60% maximum NCD regardless of claims history. DBS, by contrast, only protects the discount for one year. If you're comparing plans mainly on long-run cost rather than the headline premium, the NCD protection terms are worth reading as closely as the price.
Excess and courtesy car terms vary more than the premiums do
The plans on this list cluster fairly closely on core comprehensive coverage, but diverge sharply on what happens immediately after an accident. Courtesy car provision ranges from 7 days (DBS) up to a market-leading 30 days (AXA and Standard Chartered). Excess for younger drivers varies even more: HSBC's typical excess for under-25 drivers is HKD 10,000, above the HKD 8,000 industry average cited for that plan, while DBS charges HKD 6,000 for drivers aged 21-24. For a younger driver or someone who wants to be back on the road quickly after a claim, these terms are often more decisive than the base premium.
What newcomers to Hong Kong car insurance get wrong
The most common mistake is assuming a bank-affiliated insurer automatically offers the best value for an existing customer of that bank — the bundling discounts are real (HSBC's up to 15% multi-policy discount, for example), but they don't always offset weaker terms elsewhere in the policy, like a smaller approved workshop network or a longer claims turnaround. FWD's pay-as-you-drive option, for instance, suits low-mileage drivers well but works against anyone who drives more than 10,000 km a year. The workshop network size is also easy to overlook: a cheaper premium is less useful if the nearest approved repair shop is inconvenient, as flagged for FWD's Hong Kong Island-concentrated network and Hang Seng's limited New Territories coverage.
Related Videos
Rank it your way
Remix this list into your own ranking, or head to the play hub for every game mode and community breakdown — blind mode, challenges, tier lists, and more.
You Might Also Like
Top 10 Best Bank Accounts With the Most Perks in Hong Kong
Top 10 Best Bank Accounts With the Most Perks in Hong Kong
Top 10 Best Fixed Deposit Rates in Hong Kong (6-Month) — July 2026
Top 10 Best Fixed Deposit Rates in Hong Kong (6-Month) — ...
Top 10 Best Business Banking Accounts in Hong Kong 2026
find business banking accounts in Hong Kong
Top 10 Swiss Reinsurance Giants
#1 Swiss Re · #2 Zurich Insurance Group · #3 Swiss Life Group
Top 10 Most Overrated Tax Strategies
#1 The Augusta Rule (Section 280A) · #2 Forming an LLC for Tax Write-Offs · #3 Cost Segregation on Small Rentals
Top 10 Most Controversial Crypto Projects
#1 Terra/Luna · #2 Tether (USDT) · #3 Ripple (XRP)