Top 10 Fintech Apps in 2026
In 2026, the right money app can save you hundreds in fees and hours of frustration — but the fintech space is crowded with overlapping options that all claim to be essential. This list ranks ten apps that span the category, from all-in-one banking super-apps to focused tools for budgeting, investing, and moving money internationally, based on what each one actually does well and where it falls short. Whether you want to invest spare change, budget smarter, or send money abroad cheaply, this list has you covered.
Top10Grid lets the community re-rank anything — this order is our editors' pick for now; use the buttons below to vote it up or down.

Current Rankings
- –#1
Revolut
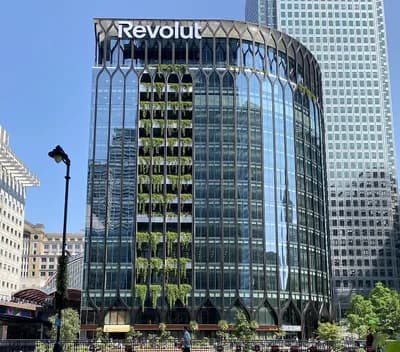
Revolut set out to replace your entire banking stack with one app, and for frequent travelers it mostly works — instant currency conversion at interbank rates, a debit card that doesn't flinch at borders, stock trading and crypto bolted onto the same account. The travel perks on the higher tiers, like lounge access, are the real reason people upgrade. The catch is what happens when something goes wrong: customer support can be slow to respond, even if you're paying for Premium, which matters more for a bank than for almost any other kind of app.
- –#2
Nubank
Nubank is Latin America's largest digital bank, built in Brazil around a no-fee purple credit card and now serving over 100 million customers across Brazil, Mexico and Colombia. It operates without branches, and its deposit accounts pay a share of Brazil's CDI benchmark rather than a fixed rate, so the yield moves with the central bank. It has been listed on the New York Stock Exchange since 2021.
- –#3
Chime
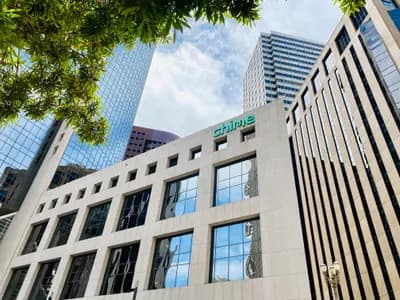
Chime is one of the largest US neobanks, offering fee-free banking with no monthly fees or minimum balances. Its SpotMe feature covers overdrafts up to $200 with no fee for members receiving qualifying direct deposits, and paychecks can arrive up to two days early via direct deposit. In September 2025, Chime retired its Credit Builder secured card in favor of the Chime Card, which keeps the no-credit-check credit-building model and adds cash-back rewards. The app has no physical branches and no built-in investing, so users need a separate brokerage account for that.
3 - –#4
Monzo
Monzo has evolved from a UK challenger bank into a full-featured financial platform with over 9 million users. Its 'Monzo Plus' account (£5/month) offers virtual cards, premium budgeting insights, and cashback on selected retailers. The 'Monzo Premium' tier adds travel insurance, phone insurance, and a higher cashback rate. Key features include 'Pots' for goal-based savings with interest paid on balances, real-time spending notifications, and the ability to freeze and unfreeze cards instantly. Monzo's 'Borrow' feature offers personal loans up to £25,000. Best for UK residents who want a modern, transparent banking experience. A notable weakness is its limited international functionality outside the UK and EU, and higher-tier fees can add up for basic users.
- –#5
Robinhood
Robinhood is the app that made commission-free trading normal, and its Gold tier is the rare upsell that's actually worth $5 a month if you keep uninvested cash sitting around or trade options. What it still won't do matters, too: no mutual funds, and its options support stops well short of the complex multi-leg strategies serious traders build. Fine for a first brokerage account, less convincing once your needs outgrow it.
- –#6
Stripe
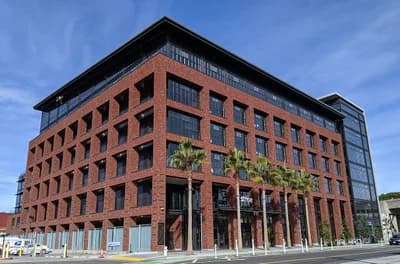
Stripe is the backbone of online commerce in 2026, powering payments for millions of businesses globally. Its 'Stripe Connect' platform enables marketplaces and platforms to manage payouts with automated compliance. Pricing runs a percentage plus a small flat fee per successful card transaction, with lower effective rates for high-volume merchants. Key features include 'Stripe Tax' (automatic sales tax calculation), 'Stripe Issuing' (create and manage virtual and physical cards), and 'Stripe Climate' (contribute a percentage of revenue to carbon removal). The 'Stripe Terminal' allows in-person payments with a compact countertop card reader. Best for e-commerce businesses, SaaS companies, and platforms of all sizes. A notable weakness is the complexity of its API for non-developers, and payout delays can occur for new accounts during risk reviews.
2 - –#7
Betterment
Betterment is one of the original robo-advisors. Its 'Digital' plan charges 0.25% of AUM for automated portfolio management; 'Premium' costs 0.65% total (the 0.25% base plus a 0.40% add-on) and adds unlimited access to certified financial planners. The main features are automated tax-loss harvesting (Betterment's own research claims this can add up to 0.77% a year after tax - that is the firm's figure, not an independent one), goal-based investing with risk assessment, and factor-tilted portfolios. It also offers a cash account and a debit card with no foreign transaction fees; check the current APY, which moves with rates. Best for long-term investors who want hands-off, tax-efficient management. Weaknesses: the fee is high relative to DIY index investing, and there is no individual stock trading.
Sourcesbetterment.com1 - –#8
Klarna
Klarna has expanded beyond BNPL into a comprehensive shopping and payments app with more than 119 million active users globally. Its 'Pay Now' option lets shoppers pay in full instantly, sometimes with retailer promotions, while 'Pay in 4' remains interest-free for short-term purchases. The 'Klarna Card' (virtual and physical) allows users to combine payments from any retailer with a single credit line. Key features include price drop alerts that can trigger a refund if an item's price falls after purchase, a 'Wishlist' feature that tracks prices across multiple stores, and 'Klarna Insights' which analyzes spending patterns to suggest budgeting improvements. Pricing is free for users, with late fees capped at a modest flat amount for missed payments. Best for online shoppers who want flexibility and rewards. A notable weakness is the potential for overspending due to easy credit access, and the app's credit check can impact credit scores.
Sourcesen.wikipedia.org1 - –#9
Wise
Wise (formerly TransferWise) is the go-to app for international money transfers, processing billions of dollars in cross-border transactions every month. Its pricing model is transparent: a low percentage fee that varies by currency, with no hidden markups on exchange rates. Key features include 'Wise Account' which holds balances in dozens of currencies, a debit card that automatically converts at the mid-market rate when spending abroad, and 'Wise Business' for multi-currency invoicing and batch payments. The app supports transfers to a wide range of countries with real-time tracking. Best for expats, freelancers, and small businesses that regularly send or receive money internationally. A notable weakness is that the user interface can feel utilitarian compared to consumer-focused neobanks.
2 - –#10
YNAB (You Need A Budget)
YNAB remains the gold standard for proactive budgeting, with a devoted user base. Its methodology is based on 'giving every dollar a job,' helping users break the paycheck-to-paycheck cycle. Pricing is $14.99/month or $109/year after a 34-day free trial. Key features include real-time sync with thousands of financial institutions, goal tracking for debt payoff and savings, and 'Age of Money' metric that shows how long your cash has been sitting in your account (a measure of financial stability). The app's 'Reports' feature provides detailed spending breakdowns by category and month-over-month comparisons. YNAB also offers live workshops and a supportive community forum. Best for individuals and couples who want to take full control of their finances through disciplined budgeting. A notable weakness is the steep learning curve for new users, and the subscription cost is higher than many free budgeting apps.
Sourcesynab.com1
Frequently Asked Questions About Fintech Apps
What is a fintech app? A fintech (short for financial technology) app is a mobile or web tool that helps you manage your money — such as banking, investing, budgeting, or sending cash abroad — usually with lower fees and a simpler experience than a traditional bank.
Are these fintech apps safe to use? Yes. Every app on this list uses bank-grade encryption and is regulated in its home market. For extra security, always turn on two-step verification (the app will walk you through it in under a minute).
Which fintech app is best for beginners? Chime and Monzo are the friendliest starting points: no monthly fees, no minimum balance, and straightforward dashboards that make it easy to see where your money goes each week.
Neobank, Payments Rail, or Budgeting Tool — They're Not All Solving the Same Problem
This list mixes three genuinely different categories of product under one "fintech app" label. Revolut, Nubank, Chime, and Monzo are neobanks — they want to be your primary account. Stripe and Klarna sit on the other side of a transaction, moving money between businesses and consumers rather than holding your paycheck. Robinhood, Betterment, and YNAB are tools for a specific job — trading, automated investing, budgeting — that assume you already bank somewhere else. Comparing them head-to-head on "which is best" only makes sense once you know which of those three jobs you actually need done.
What a Newcomer Gets Wrong About "Free" Fintech Apps
Nearly every app on this list advertises a free tier, which makes them look interchangeable on price. They aren't. Some make money on interchange fees merchants pay when you swipe (the neobanks), some on a cut of every transaction they process (Stripe, Klarna), and some on a subscription for the features that actually change your financial outcome (Betterment's advisory fee, YNAB's subscription). "Free" describes the entry point, not the business model — worth knowing before you assume the free tier of any one of these is the full product.
Image credits
- Revolut: London Revolut.jpg / Wikimedia Commons
- Nubank: Nubank logo 2021.svg / Wikimedia Commons
- Monzo: Monzo 2022 logo.svg / Wikimedia Commons
- Stripe: Stripe headquarters (San Francisco, 2019) -2.jpg / Wikimedia Commons
- Wise: Wise Logo 512x124.svg / Wikimedia Commons
Related Videos
Frequently asked questions
What criteria were used to rank the Top 10 Fintech Apps in 2026?
The ranking is based on a combination of user ratings, active user base, security features, innovative technology, and overall financial management capabilities as of 2026.
Are the top fintech apps in 2026 free to use?
Most top fintech apps offer free basic accounts, but premium features such as advanced budgeting, investment insights, or real-time spending analytics may require a paid subscription.
How do these fintech apps ensure the security of my financial data?
Leading fintech apps in 2026 employ bank-grade encryption, multi-factor authentication, and often comply with regulations like GDPR and SOC 2 to protect user data and transactions.
Which app in the Top 10 list is best for budgeting and expense tracking?
While specific rankings may vary, apps like Mint, YNAB, or Cleo frequently top the list for budgeting due to their automated categorization, goal setting, and real-time spending alerts.
Rank it your way
Remix this list into your own ranking, or head to the play hub for every game mode and community breakdown — blind mode, challenges, tier lists, and more.
You Might Also Like
Top 10 European FinTech Unicorns Ranked by Valuation (2025–2026)
Top 10 European FinTech Unicorns Ranked by Valuation (202...
Top 10 Best Banking Apps
Top 10 Best Banking Apps
Top 10 Best Fintech Companies
Top 10 Best Fintech Companies
Top 10 Most Controversial Billionaire Wealth
#1 Elon Musk — $250B+ Net Worth · #2 Jeff Bezos — $200B+ Net Worth · #3 Bernard Arnault — $190B+ Net Worth
Top 10 CoinGecko — Top Cryptocurrencies — March 20, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)
Top 10 Best Personal Finance Books
#1 The Psychology of Money by Morgan Housel · #2 The Intelligent Investor by Benjamin Graham · #3 Rich Dad Poor Dad by Robert Kiyosaki