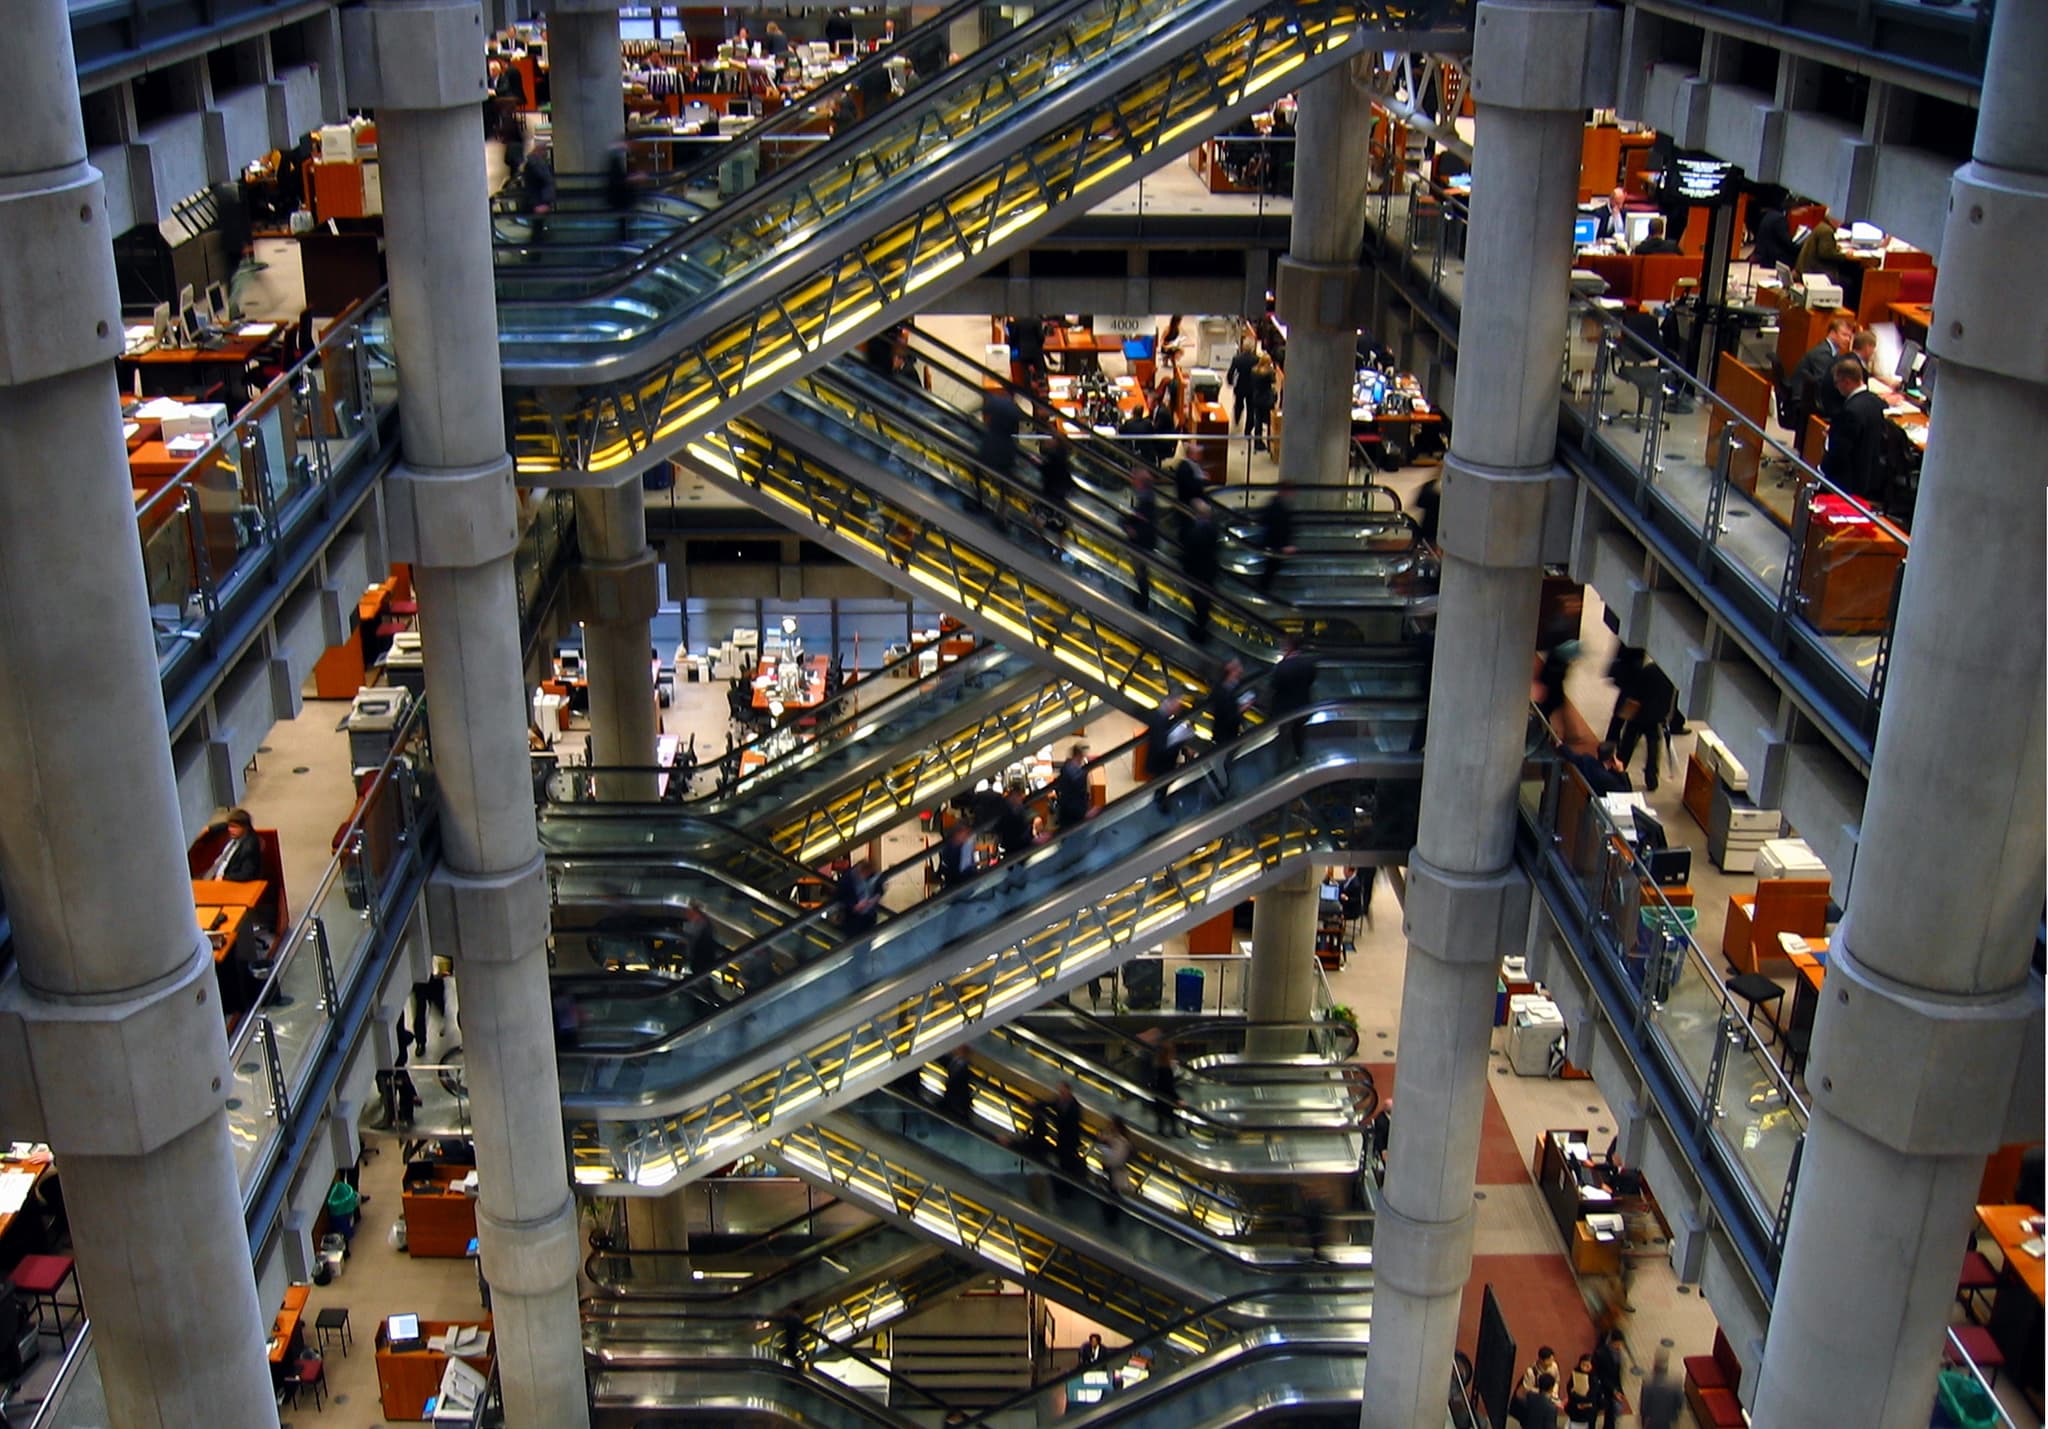
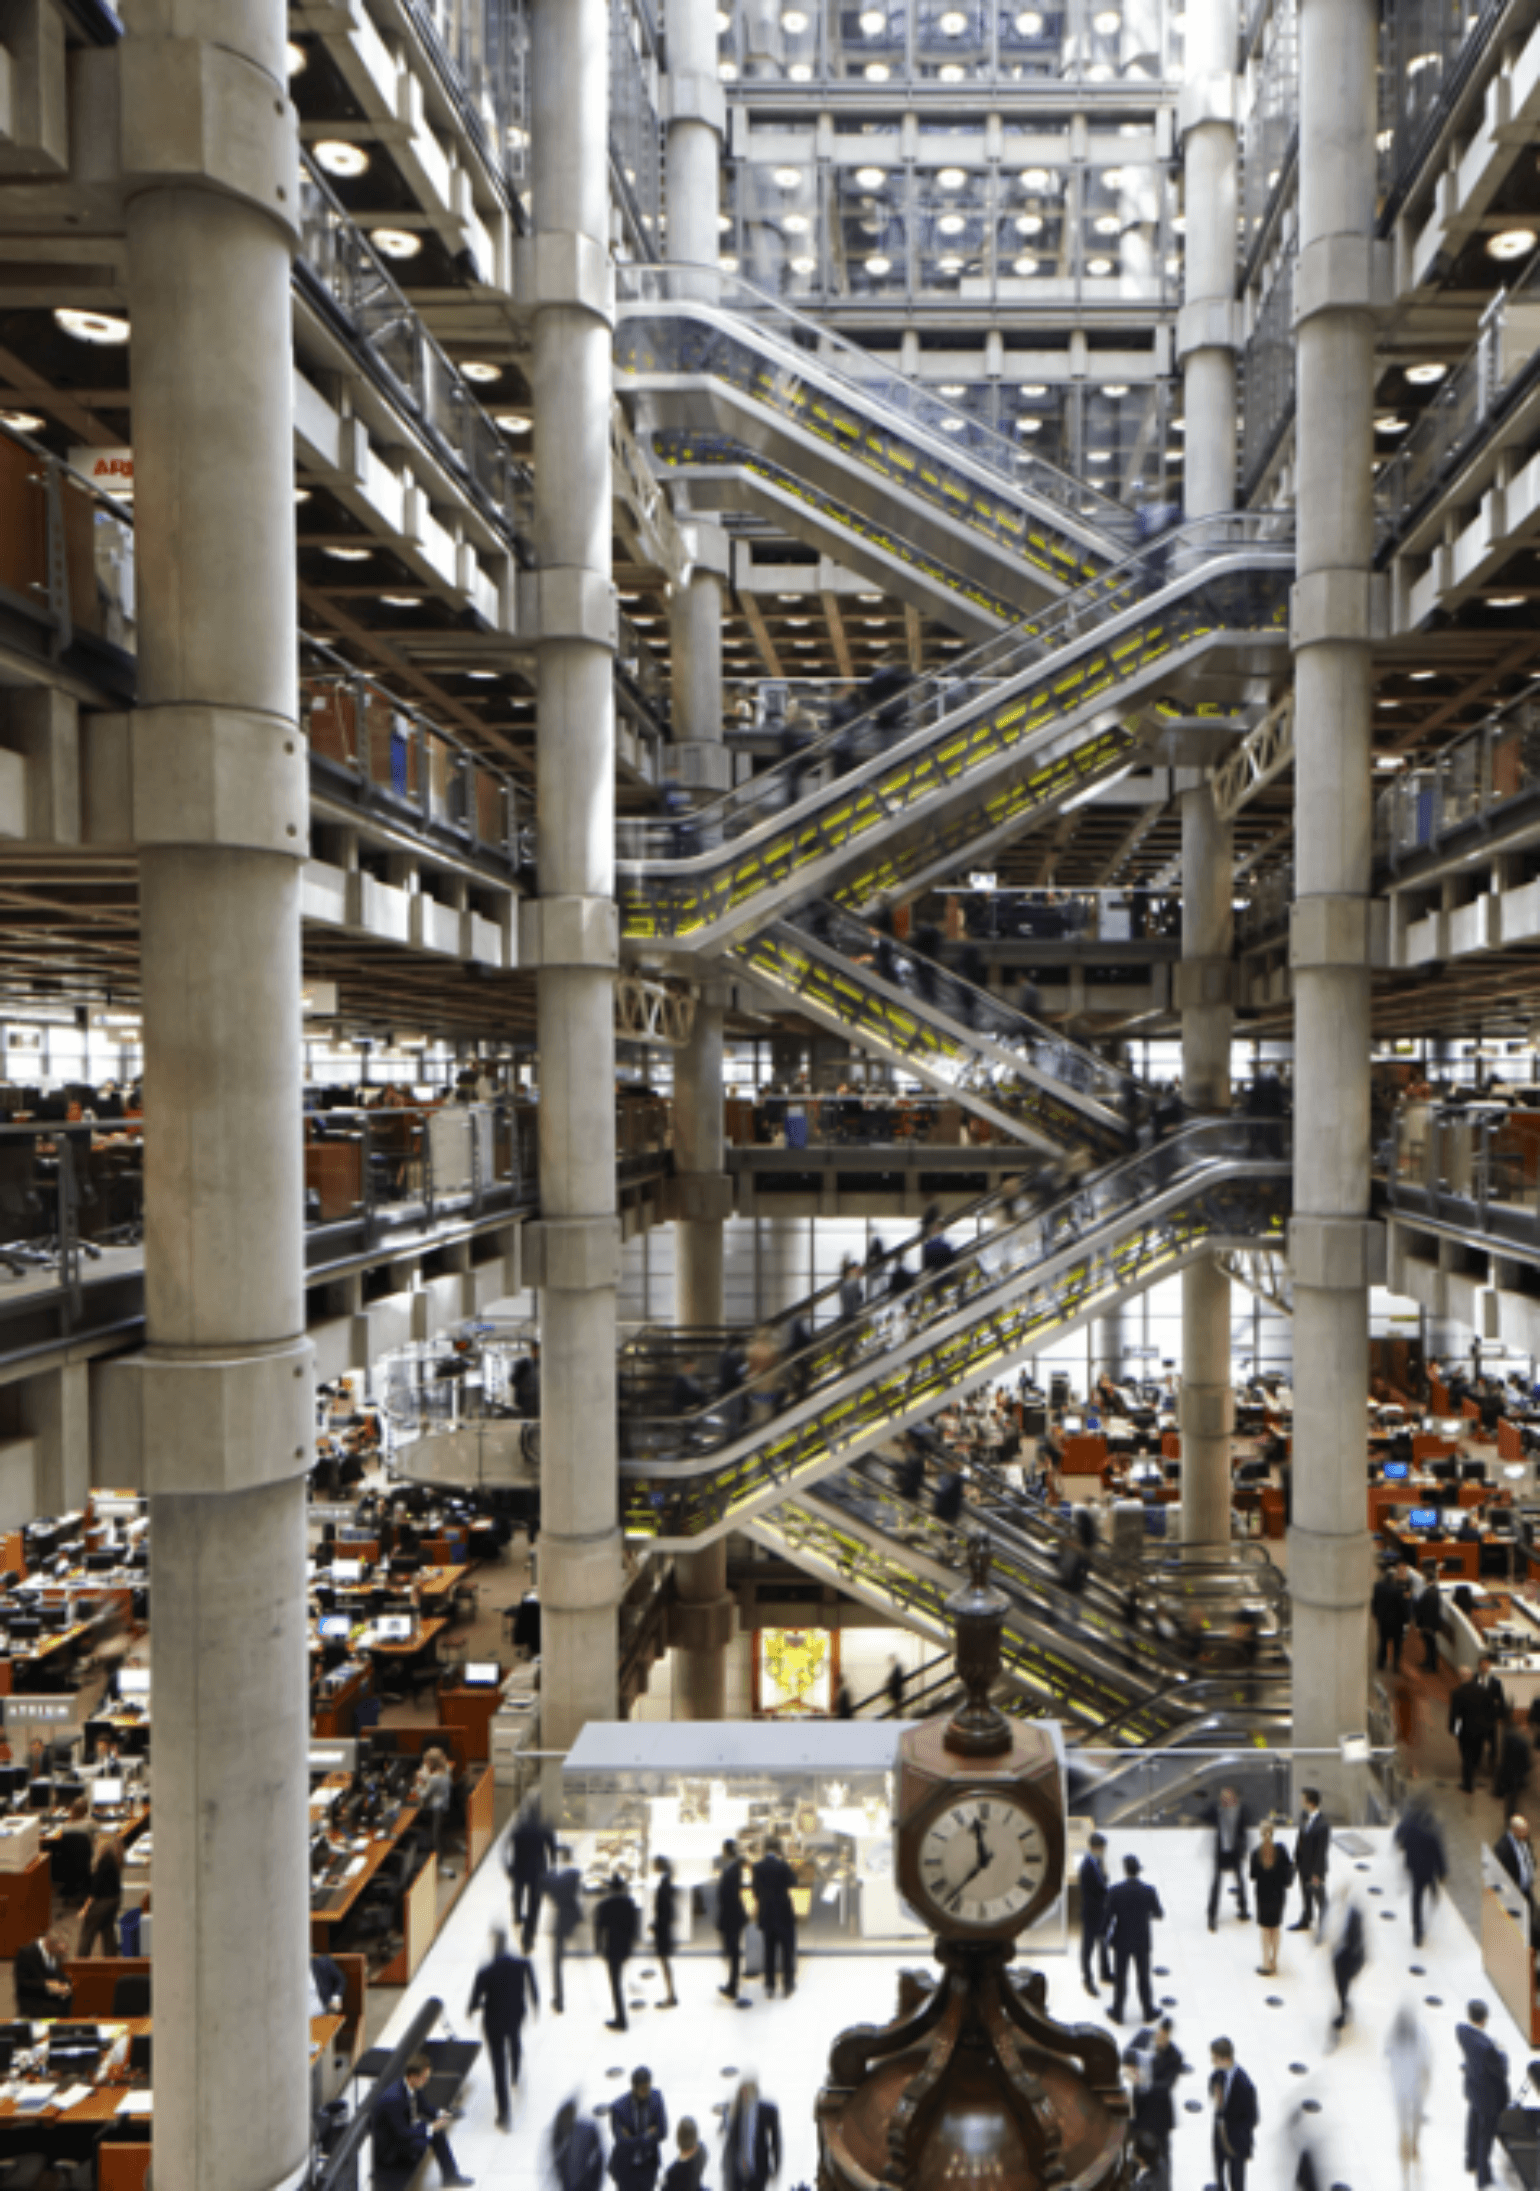
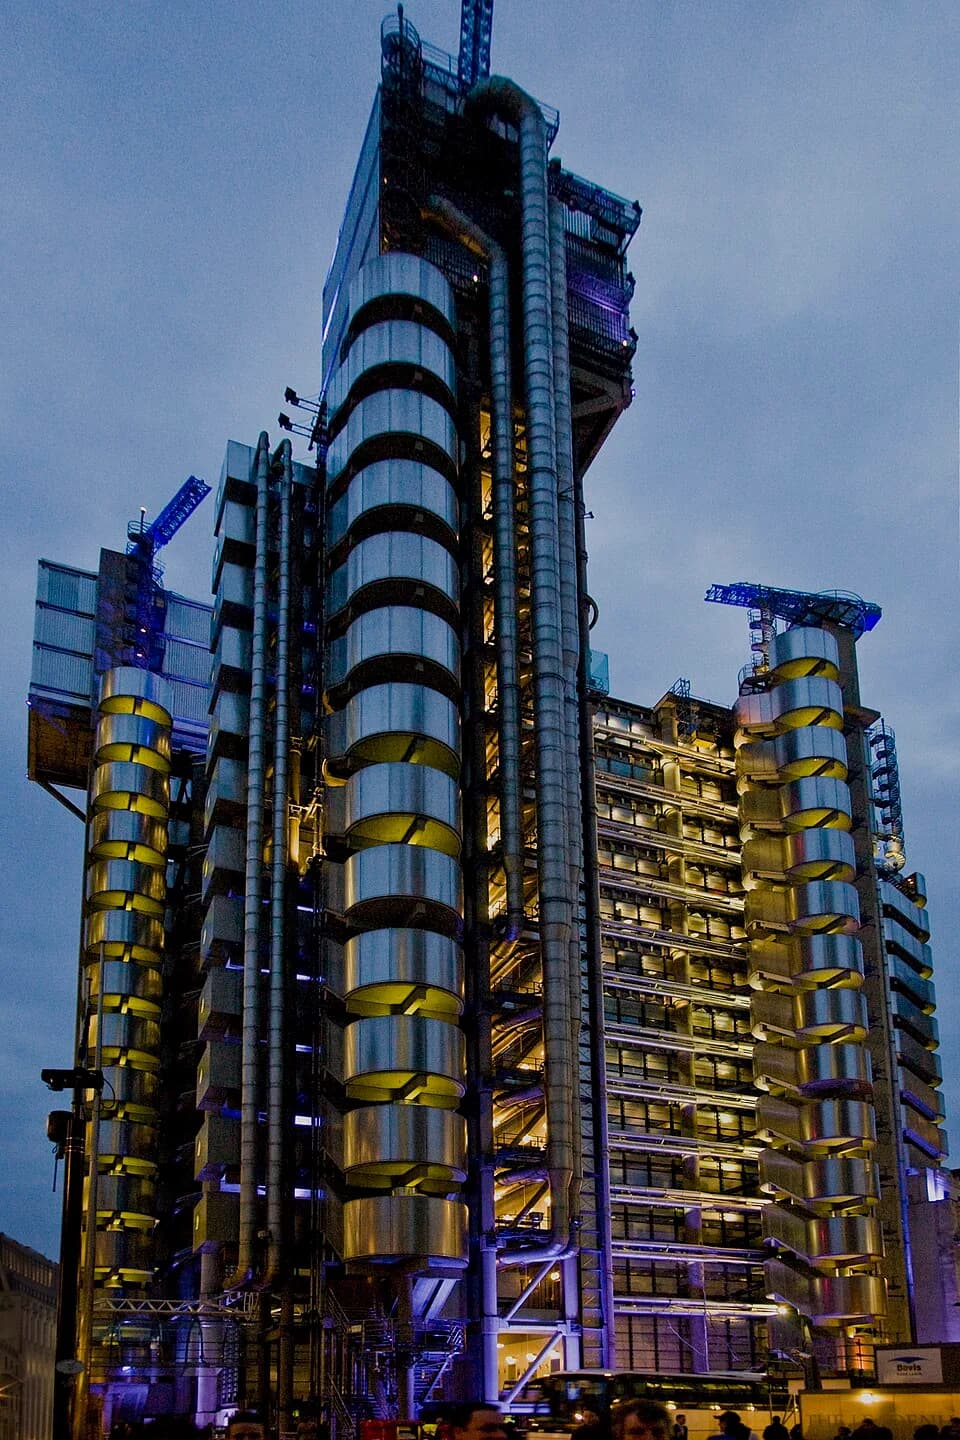
phogel from germany / Wikimedia Commons (CC BY-SA 2.0)
Top 10 Lloyd's of London Syndicates
Lloyd's of London's 76 syndicates generate over £52 billion annually in premium, but which ones truly lead the market? From cutting-edge cyber underwriters navigating AI-driven risk to established energy specialists managing geopolitical volatility, the most successful Lloyd's syndicates combine deep technical expertise, financial muscle, and adaptability in an increasingly digital marketplace. With the 2025 Blueprint Two programme now processing 90%+ of risks electronically, today's top syndicates leverage automation and innovation to outpace competitors. In this guide, we profile the 10 Lloyd's syndicates earning the highest reputation for market innovation, capacity, and underwriting excellence—and why they dominate their specialties.
2026254 views
Top10Grid rankings are decided by votes, not algorithms — use the buttons below to move this list.
Current Rankings
Vote items up or down — rankings update instantly
Get the weekly finance rundown
Only lists published since the last email. Join the early readers.
- Only Top 10s published in the last 7 days
- One email a week — and none at all in a week with nothing new
- Unsubscribe in one click
No spam. One email per week. Unsubscribe anytime.
What a Lloyd's Syndicate Actually Is
Lloyd's of London isn't an insurance company in the usual sense — it's a marketplace, and each syndicate inside it is a separate pool of underwriting capacity, backed by its own capital providers and run day-to-day by a managing agent. Multiple syndicates frequently sit on the same risk together, one acting as the "lead" that sets terms and pricing and the others "following" on the same policy, so a risk that looks like it belongs to a single syndicate is often shared across several.
Size, measured in gross written premium, is a rough proxy for market presence but not for expertise in any particular line. Specialty classes like cyber, aviation, or marine tend to be dominated by a handful of syndicates known specifically for underwriting depth in that line, and a broker placing a specialty risk usually cares more about that track record than about a syndicate's overall size.
How to Read a Syndicate's Standing, Not Just Its Size
The combined ratio — claims and expenses paid out as a percentage of premium collected — is the clearest single signal of underwriting discipline available for any syndicate. A ratio under 100% means the syndicate made an underwriting profit before investment income is even counted; a ratio at or above 100% means it's relying on investment returns, or simply losing money, to stay profitable.
Premium growth needs the same scrutiny. A syndicate writing more premium year over year can mean genuine market leadership — winning business on merit — or it can simply mean more capital chasing the same risks in a hardening market, where prices are rising broadly and everyone's premium figures grow together. The two look identical on a chart and mean very different things about a syndicate's actual standing.
How the Lloyd's market actually works
Lloyd's of London isn't an insurance company in the ordinary sense — it's a marketplace. Independent syndicates, each backed by their own capital providers (historically wealthy individual "Names," now overwhelmingly corporate and institutional capital), compete for business and sometimes co-insure the very same risk alongside each other. That structure is why the Corporation of Lloyd's itself sits apart from the syndicates it hosts: it provides the market's infrastructure and oversight rather than underwriting policies directly.
Gross written premium measures how much business a syndicate writes, not how profitable that business is. The number worth weighing against it is the combined ratio — claims plus expenses as a share of premium collected. Under 100% means the syndicate is making an underwriting profit before investment returns; over 100% means it's relying on investment income from its reserves to be profitable overall.
A syndicate's financial-strength rating from an agency like AM Best or S&P matters most for large or long-tail claims — the kind that surface years or decades after a policy is written, where the insurer needs to still exist, and still be solvent, to pay out.
Common questions
Is a bigger GWP number always better? Not necessarily. A syndicate specializing narrowly in a technical line — offshore energy, aviation hull — can carry far more expertise per dollar written than a broad generalist with a larger book. Scale and specialization are different kinds of strength.
What actually happens if a syndicate can't pay a claim? Lloyd's maintains a central guarantee fund precisely for this scenario, funded by all syndicates collectively — it's part of why the market as a whole carries strong ratings even when individual syndicates vary.
Readers Also Ranked
More Lists Like This
Top 10 European Investment Banks 2026
- #1BNP Paribas CIB
- #2Deutsche Bank
- #3UBS Group
Top 10 US Investment Banks by Revenue 2026
- #1JPMorgan Chase
- #2Bank of America
- #3Wells Fargo
Top 10 Most Valuable Companies in the World 2026
- #1Apple
- #2NVIDIA
- #3Microsoft
10 Best HKD Time Deposit Rates in Hong Kong (June 2026) — Earn Up to 4.50% on HKD 100,000
- #1HKD Time Deposit - ZA Bank
- #2HKD Time Deposit - Mox Bank
- #3HKD Time Deposit - WeLab Bank
Frequently asked questions
What is a Lloyd's of London syndicate?
A Lloyd's syndicate is a group of underwriters or investors that join together to accept insurance risks, each syndicate specializing in certain lines of business and managed by a managing agent.
How are the top 10 Lloyd's syndicates determined?
They are typically ranked by financial metrics such as gross written premium, capacity, profitability, or market share, as reported by Lloyd's annual results or industry analyses.
Who are the largest syndicates at Lloyd's of London?
The largest syndicates often include names like Hiscox, Brit, Chaucer, Catlin (now part of XL Catlin), and Liberty Mutual, though the exact ranking changes yearly based on underwriting performance and capacity.
What is the difference between a Lloyd's syndicate and a traditional insurance company?
A Lloyd's syndicate is a temporary partnership of investors that underwrites risks for one year and is not a separate legal entity, whereas a traditional insurance company is a permanent corporation that assumes risk on its own balance sheet.
Can individual investors join a Lloyd's syndicate?
Historically, wealthy individuals (Names) could join as members, but today most capital comes from corporate investors, and individual participation is now limited through special vehicles or funds.
Discussion
Have a take on this ranking?
Comments are how the argument actually happens here. Posting one needs a free account — it takes about a minute.
No comments yet.
The first comment sets the terms of the argument.
Would your top 10 look different?
Publish your own ranking of this topic. Your list gets its own page, and readers vote on it the same way you just voted on this one.
Build your own Top 10You might also want to rank…
 Top 10 US Auto Insurance Companies 2026
 Top 10 CoinGecko — Top Cryptocurrencies — April 24, 2026
 Top 10 Cryptocurrencies by Market Cap (CoinGecko Snapshot, April 5, 2026)
 Top 10 Biggest Stock Market Crashes That Destroyed Fortunes — And What Actually Caused Them
Explore more Finance rankings on Top10Grid
People Also Explore
Because you're viewing Finance
Top 10 European Hedge Funds by AUM
190 views · 0 votes
Top 10 US REIT Companies by Market Cap
191 views · 0 votes
Top 10 US Robo-Advisors 2026
191 views · 0 votes
Top 10 US Microfinance Institutions
196 views · 0 votes
Best Personal Loans in Hong Kong (2026): Lowest APR, Highest Limits & Fastest Approvals
198 views · 0 votes
Top 10 European Quantitative Finance Firms
200 views · 0 votes
You might also like
FINANCESame type
Top 10 UK Insurance Groups 2026
10 items
FINANCESame type
Top 10 European Reinsurers by Net Premium Written
10 items
FINANCESame type
Top 10 Swiss Reinsurance Giants
10 items
FINANCESame type
10 Best Personal Accident Insurance Plans in Hong Kong (2026) — Coverage & Premium Compared
10 items
FINANCESame type
Top 10 Most Affordable Travel Insurance Plans in Hong Kong
10 items
FINANCESame type
Top 10 European Climate Insurance Initiatives
10 items