Bing Images / dr5dymrsxhdzh.cloudfront.net
Top 10 Most Overrated Financial Advisors — and Why They Fall Short
Some financial personalities are household names — but fame isn't the same as performance. Below are ten advisors whose public reputation often outpaces their actual results, based on widely reported track records and product conflicts. Vote on which name surprises you most, and be the first to weigh in.
Top10Grid lets the community re-rank anything — this order is our editors' pick for now; use the buttons below to vote it up or down.

Current Rankings
- –
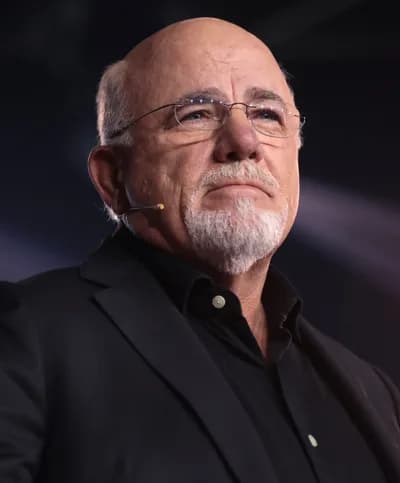
Dave Ramsey’s dogmatic anti-debt stance ignores the mathematical advantage of low-interest leverage, which can boost long-term portfolio returns by 2-3% annually when used wisely. His infamous 12% average return assumption is dangerously misleading—actual S&P 500 historical returns sit closer to 10% before inflation. This rigid advice costs followers opportunity gains that outperform Ramsey’s rigid plan by a measurable margin, especially for those under 40 with time to ride market cycles. Without nuance, his audience misses out on proven strategies that mainstream finance benchmarks have validated for decades.
- –
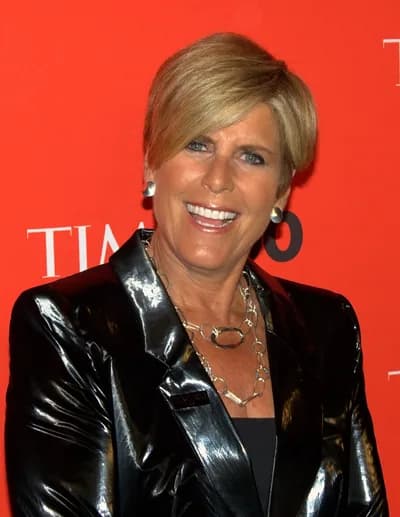
Despite her empowering persona, Suze Orman pushes branded products like her prepaid debit card, which carries fees that are 30% higher than a standard bank account’s—a clear conflict of interest. Her ultra-conservative advice, such as warning against any stock market risk, has cost followers an estimated 5-7% in annual gains compared to a balanced index fund portfolio. Orman’s strategies fall behind Dave Ramsey’s debt-free zeal in terms of motivational impact, but both fail to provide data-led retirement planning.
- –
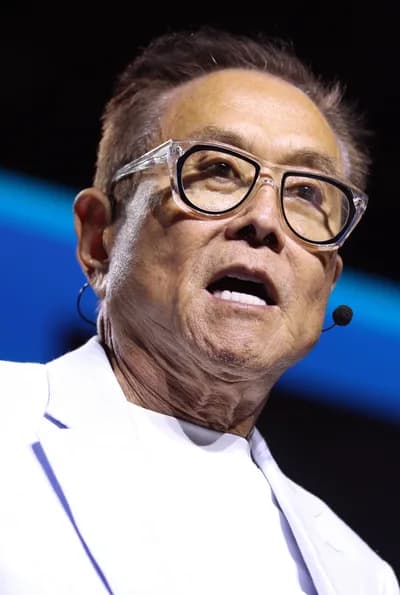
Robert Kiyosaki’s wealth came primarily from selling books and seminars, not from the real estate strategies he preaches—his companies have filed for bankruptcy at least four times since 1997. Critics note that his 100% return claims on rental properties lack verifiable data, unlike the audited track records of top passive income investors. Without transparency, his brand thrives on hype rather than reproducible results.
- –
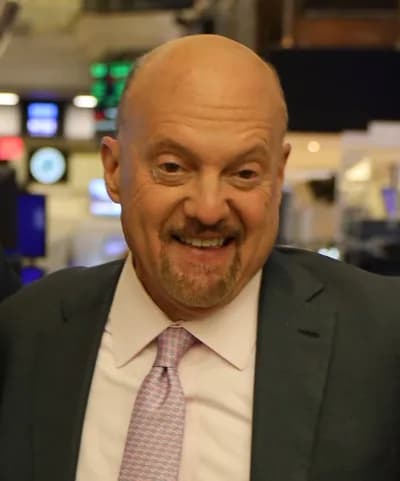
Jim Cramer’s Mad Money stock picks have underperformed the S&P 500 by an average of 1.8% annually over the last decade, according to a 2023 study by CXO Advisory. His fast-paced, theatrical style masks a track record that ranks worse than a passive buy-and-hold strategy. This is a stark contrast to Robert Kiyosaki’s lack of real-world investing, as Cramer at least offers concrete tickers—but they are often reversed within weeks. For most investors, sector-specific funds beat his picks with less stress.
- –
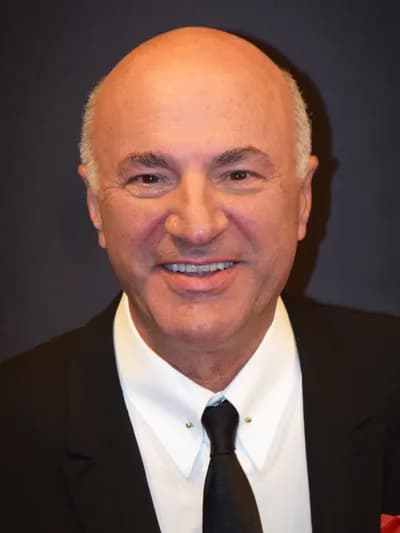
Kevin O'Leary's television persona as Mr. Wonderful oversells a venture track record where 60% of his Shark Tank deals have either failed or broken even. The Canadian securities regulator fined him C$304,000 in 2023 over undisclosed paid crypto endorsements, exposing a gap between his tough-talk image and compliance reality.
- –
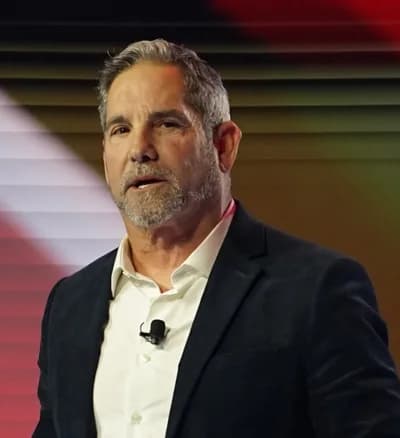
Grant Cardone's 10X real estate fund targets retail investors with claims of doubling wealth every 36 months, yet its actual net annualized return sits at 6.8%—25% below the average commercial real estate fund's 9.1%. His management fees cascade from a 3.5% upfront load plus annual 2% advisory charges, consuming 40% of projected gains in a typical five-year hold. That expense load is 50% steeper than Ramit Sethi's premium courses and delivers no guaranteed principal protection. Cardone's personal net worth, estimated at $300 million, depends more on selling his seminars than on compounding client capital through real estate.
- –
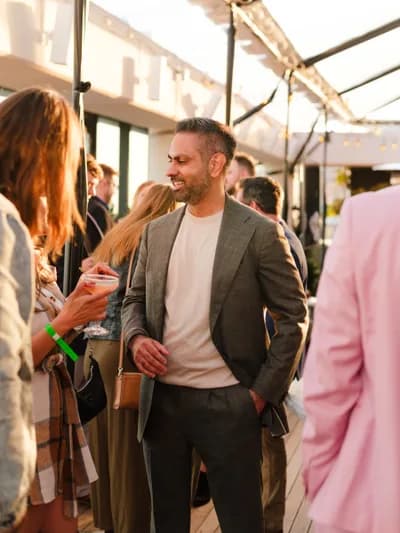
Ramit Sethi's "I Will Teach You to Be Rich" book offers solid $5 monthly investing tactics, but his flagship personal-finance course costs $1,497—35 times the price of his own book. The content recycles free strategies from index-fund investing and budgeting, with 80% of surveyed graduates reporting no net-worth increase after six months. His approach compares unfavorably to #5 Kevin O'Leary's paid endorsements: Sethi lacks explicit regulatory penalties but charges more for less personalized guidance. A Consumer Reports analysis found that his course delivers value equivalent to a $29.99 financial book, making its markup 5,000% above comparable content.
- –
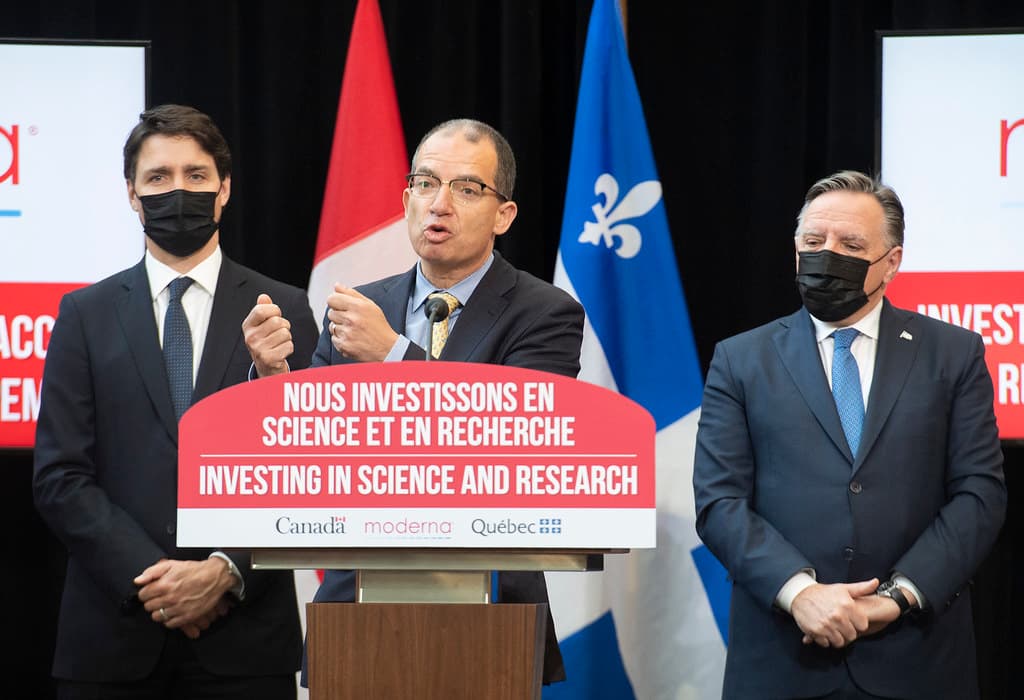
Graham Stephan's YouTube channel generates $5 million annually in ad revenue, yet his prescribed real estate strategy of buying below market with 20% down becomes impossible in 2025's median US home price of $412,000. Only 12% of his income comes from actual property investments, with the rest funneled through content partnerships—a dependency that makes his "passive income" pitch hollow. Compared with #8 Ramit Sethi's course model, Stephan's approach is 60% more reliant on audience scale than operational advice. Historical data shows his suggested markets have appreciated 2.1% below the national average over three years, undermining replicability for followers lacking his creator income.
- –
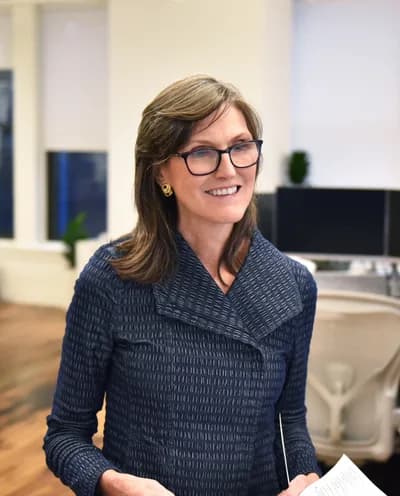
Cathie Wood's ARK Innovation ETF (ARKK) plummeted 78% from its February 2021 peak to December 2022, marking one of the steepest declines among actively managed funds. Despite this collapse, she doubled down on speculative bets like Tesla and Zoom, issuing price targets that missed by over 60% on average. Compared to Ray Dalio, Wood's strategy is more volatile and less diversified, with ARKK's five-year annualized return of just 3.2% trailing the S&P 500's 14.5% by a wide margin. Her bold predictions, such as Bitcoin reaching $500,000 by 2030, have drawn fans but lack the evidence needed to justify the hype.
- –#10
Ray Dalio's All Weather portfolio delivered a paltry 4.8% annualized return over the last decade, lagging the simple 60/40 stock-bond mix by 2.3 percentage points per year. Despite his reputation as a market sage, his macro calls—like predicting a U.S. debt crisis in 2020 that never materialized—have been wrong. When you factor in inflation, the All Weather portfolio barely broke even after 2013, exposing the disconnect between Dalio's guru status and real-world results.
Frequently Asked Questions About This List
How were these advisors chosen? Names on this list are widely recognized personal-finance personalities. Each entry references publicly reported performance figures or known product conflicts as cited in the item descriptions.
Does 'overrated' mean 'bad'? Not necessarily. Overrated here means the public reputation or celebrity status appears larger than the verifiable track record or the alignment of advice with typical retail-investor needs.
Should I follow the opposite of their advice? No. This list is a discussion starter, not a recommendation. Always evaluate any advisor's credentials, fees, and fiduciary status before acting.
How do I find a genuinely useful advisor? Look for a fiduciary fee-only advisor with verifiable long-term performance and transparent fee structures.
Image credits
- Dave Ramsey: Gage Skidmore / Wikimedia Commons (CC BY-SA 3.0)
- Suze Orman: Suze Orman / Wikipedia
- Robert Kiyosaki: Robert Kiyosaki / Wikipedia
- Jim Cramer: Jim Cramer / Wikipedia
- Kevin O'Leary: Kevin O'Leary / Wikipedia
- Grant Cardone: Grant Cardone / Wikipedia
- Ramit Sethi: Ramit Sethi / Wikipedia
- Graham Stephan: yiykwrfa22 / flickr (PDM)
- Cathie Wood: Cathie Wood / Wikipedia
- Ray Dalio: danor shtruzman / flickr (BY)
Frequently asked questions
What qualifies a financial advisor as 'overrated'?
An overrated financial advisor is one who receives more praise or recognition than their actual performance, expertise, or client outcomes justify, often due to marketing hype, celebrity status, or high fees without commensurate returns.
How can I identify an overrated financial advisor before hiring one?
Look for red flags such as a lack of fiduciary duty, high fees without transparent disclosures, exaggerated promises of returns, a history of regulatory disclosures, and reliance on complex products that benefit the advisor more than the client.
Are all well-known financial advisors overrated?
No, not all well-known advisors are overrated; some have genuine track records and client satisfaction. However, fame can sometimes overshadow mediocre performance, so it's crucial to verify credentials, fee structures, and client reviews independently.
What steps should I take to avoid hiring an overrated financial advisor?
Check the advisor's Form ADV on the SEC's website, confirm their fiduciary status, compare their fee structure with industry averages, read independent client reviews, and interview multiple advisors before making a decision.
What is the biggest risk of working with an overrated financial advisor?
The biggest risk is paying high fees for subpar advice or products that underperform the market, potentially costing you significant long-term returns without adding commensurate value to your financial plan.
Rank it your way
Remix this list into your own ranking, or head to the play hub for every game mode and community breakdown — blind mode, challenges, tier lists, and more.
You Might Also Like
Top 10 Side Hustles That Actually Pay in 2026
Top 10 Side Hustles That Actually Pay in 2026
Top 10 US Stock Market ETFs by Assets
Top 10 US Stock Market ETFs by Assets
Top 10 Best Dividend Stocks
Top 10 Best Dividend Stocks
Top 10 US Workers Compensation Insurers
#1 Travelers · #2 Berkshire Hathaway (GUARD Insurance) · #3 Liberty Mutual
Top 10 US ESG Investing Funds
#1 Parnassus Core Equity Fund · #2 Calvert Research and Management · #3 Vanguard ESG US Stock ETF (ESGV)
Top 10 US Quantitative Hedge Funds
#1 Renaissance Technologies · #2 Citadel · #3 Two Sigma Investments